Indexia Finance

The Ultimate Guide to NPA Loan in India: Everything You Need to Know!


In the complex landscape of corporate finance in India, loans for Non-Performing Asset (NPA) companies play a pivotal role in revitalizing struggling businesses. This article delves into the nuances of obtaining an NPA loan in India, elucidating the process, significance, challenges, and future outlook.

Understanding NPA: Full Form, Meaning, and Basics in Banking

NPAs are assets that cease to generate income for lenders due to default or non-payment by borrowers. These assets pose significant challenges to financial institutions and businesses, impacting liquidity, profitability, and overall economic stability.

Importance of NPA Loan Companies in India

Loans for NPA companies are instrumental in facilitating financial restructuring, debt resolution, and business revival efforts. By providing access to capital, these loan enable companies to address liquidity issues, restructure debts, and implement turnaround strategies.

Gross NPA vs Net NPA and Types of NPA Explained

Several types of loans cater to the specific needs of NPA companies:

1. Restructuring Loans:

  • Designed to restructure existing debts and align repayment terms with the company’s cash flow.

2. Asset Reconstruction Loans:

  • Aimed at acquiring and restructuring distressed assets for value maximization and recovery.

3. Bridge Loans:

  • Offer short-term financing to meet immediate funding requirements during the restructuring process.

Eligibility Criteria for Loans for NPA Companies

  1. Financial Stability: NPA companies need to show they’re financially stable.
  2. Collateral: They must offer collateral, like assets or personal guarantees.
  3. Recovery Plan: They should have a plan to fix their non-performing assets.
  4. Legal Compliance: They must follow all legal requirements.
  5. Viability: Lenders check if their business can succeed.
  6. Management Experience: They need experienced leaders to manage finances.
  7. Debt Coverage: Companies must prove they can cover loan payments.
  8. Exit Plan: They should have a plan to repay the loan.
  9. Transparency: Clear and honest reporting is crucial.

Checking Your CIBIL Score Before Loan Application

Understanding CIBIL Score Range and How to Check It

Before applying for corporate financing or distressed asset loans, it is vital to know your CIBIL score range. You can check your CIBIL score for free online. Understanding CIBIL score how to check methods and knowing how to CIBIL score check online gives you a clear picture of your credit health before approaching a finance company or a finance loan provider. 

Application Process for NPA Companies

  1. Contact: Borrowers reach out to NPA companies for assistance.
  2. Assessment: NPA companies assess the situation and the potential for help.
  3. Documentation: Borrowers submit financial and legal documents.
  4. Due Diligence: NPA companies verify the information and evaluate risks.
  5. Proposal: NPA companies offer a plan with terms and conditions.
  6. Negotiation: Both parties discuss and finalize the terms.
  7. Agreement: A formal agreement is signed.
  8. Implementation: The plan is put into action, with monitoring.
  9. Resolution: The goal is to resolve the distressed assets.
  10. Closure: Once resolved, the engagement concludes.

Risks and Challenges Associated with NPA Loan Companies in India

Obtaining loans for NPA companies entails certain risks and challenges:

1. High Interest Rates:

  • Due to the perceived riskiness of NPA loans, interest rates may be higher compared to standard loans.

2. Collateral Obligations:

  • Lenders often require substantial collateral to mitigate the risk of default.

3. Regulatory Compliance:

Corporate Debt Restructuring, OTS Scheme & NPA Resolution Services

Effective management of NPA loans involves implementing various strategies:

1. Debt Restructuring:

  • Negotiating with lenders to restructure debts and align repayment terms with the company’s cash flow.

2. Business Turnaround Plans:

  • Implementing comprehensive turnaround strategies to improve operational efficiency and profitability.

3. Legal Remedies:

  • Exploring legal options, such as debt recovery mechanisms and insolvency proceedings, to resolve financial distress.

Financial Planning Tools: Loan Calculator & EMI Calculators

How to Use an EMI Calculator for Loan Planning

When evaluating restructuring plans, utilizing a reliable loan calculator or an EMI calculator for loan helps you project your equated monthly installment accurately, ensuring your business cash flow can support the repayment terms.

Top NPA Loan Companies in India

RankCompanyLoan ProductsEligibility CriteriaAdditional Services
1Indexia FinancePersonal loans, business loans, mortgagesVaries based on loan product and borrower profilePersonalized financial solutions and advisory services
2State Bank of IndiaPersonal loans, home loans, etc.Based on credit score, income, and other factorsDigital banking services, wealth management, insurance, etc.
3ICICI BankPersonal loans, home loans, etc.Subject to creditworthiness and incomeInvestment advisory, online banking, wealth management, etc.
4Punjab National BankPersonal loans, business loans, etc.Based on credit history and incomeDigital banking, insurance, investment products, etc.
5Axis BankPersonal loans, business loans, etc.Eligibility criteria based on income and creditWealth management, investment banking, online trading, etc.
6Bank of BarodaPersonal loans, home loans, etc.Subject to credit score and incomeInsurance, mutual funds, investment banking, etc.
7HDFC BankPersonal loans, home loans, etc.Eligibility based on income and credit historyOnline banking, investment services, insurance, etc.
8Canara BankPersonal loans, business loans, etc.Creditworthiness and income determine eligibilityWealth management, insurance, investment banking, etc.
9Union Bank of IndiaPersonal loans, home loans, etc.Income, credit score, and employment statusOnline banking, investment services, insurance, etc.
10IDBI BankPersonal loans, business loans, etc.Creditworthiness and repayment capacityInvestment banking, insurance, online trading, etc.
11Bank of IndiaPersonal loans, home loans, etc.Creditworthiness, income, and employment statusInsurance, investment products, online banking, etc.

Future Outlook for NPA Loan Company in India

The future of loans for NPA companies hinges on regulatory reforms, economic trends, and market dynamics. Continued efforts to streamline the resolution process and enhance transparency are crucial for fostering investor confidence and facilitating loan recovery.

Conclusion

Loans for NPA companies serve as a vital lifeline for distressed businesses, enabling them to navigate financial challenges and embark on the path to recovery. By understanding the intricacies of NPA loans and implementing effective strategies, companies can emerge stronger and more resilient in the face of adversity.

Ready to tackle your NPA loan? Let us help you navigate the complexities and find the best solution for your financial needs. Contact us today to discuss your options and take the first step toward financial recovery.

Comprehensive Guide to Construction Loan in India: Everything You Need to Know

Embarking on a construction loan in India can be an exciting endeavour, but securing the right financing is crucial for success. Construction loan play a pivotal role in funding such ventures, offering tailored financial solutions for building or renovating properties. In this comprehensive guide, we’ll delve into the intricacies of a construction loan in India, covering eligibility criteria, types of loans, the application process, interest rates, risks, and success stories to empower you with the knowledge needed to navigate this financial landscape confidently.

Understanding Construction Loan in India

  • Definition: Construction loan are specialized financial products designed to provide funding for the construction, renovation, or expansion of properties.
  • Purpose: Unlike traditional home loans, construction loan offer short-term financing specifically tailored to cover the costs associated with construction loans.

Eligibility Criteria

  • Income Requirements: Lenders typically assess borrowers’ income to ensure they have the financial capacity to repay the loan.
  • Credit Score: A good credit score is essential for obtaining favourable loan terms and securing approval from lenders.
  • Property Details: Borrowers must provide comprehensive details about the property, including location, size, and proposed construction plans.

Types of Construction Loan in India

  • Plot Purchase Loans: Ideal for acquiring land for construction purposes.
  • Home Construction Loan: Designed to finance the construction of residential properties.
  • Renovation Loans: Offered for renovating or remodelling existing properties to enhance their value.

Application Process

  • Gather Documentation: Prepare necessary documents such as income proof, identity proof, property documents, and construction plans.
  • Choose Lender: Research and compare loan offerings from various lenders to find the best fit for your needs.
  • Submit Application: Complete the application process by submitting the required documents to the chosen lender.

Interest Rates and Terms

  • Determining Factors: Interest rates for construction loan may vary based on factors such as loan amount, tenure, borrower’s creditworthiness, and prevailing market conditions.
  • Loan Tenure: Construction loan typically have shorter tenures compared to traditional home loans, often ranging from one to five years.
  • Repayment Options: Lenders may offer flexible repayment options, including interest-only payments during the construction phase, followed by principal and interest payments post-construction.

Risks and Considerations

  • Cost Overruns: Construction loan are susceptible to cost overruns due to factors like material price fluctuations and unexpected delays.
  • Project Feasibility: Conduct thorough feasibility studies to assess the viability of the construction project and mitigate potential risks.
  • Timely Completion: Ensure timely completion of the project to avoid additional expenses and minimize financial strain.

Conclusion

Navigating the complexities of construction loan in India requires careful consideration and informed decision-making. By understanding the eligibility criteria, application process, interest rates, risks, and success stories outlined in this guide, you can embark on your construction journey with confidence and financial acumen. Whether you’re building your dream home or undertaking a lucrative property development venture, leveraging the power of a construction loan can turn your vision into reality.

Ready to turn your construction dreams into reality? Contact us today to explore our tailored construction loan options!

Navigating Film Finance in India: A Comprehensive Guide for Filmmakers

Film finance in India is a multifaceted landscape that plays a pivotal role in bringing cinematic visions to life. For filmmakers and producers alike, understanding the nuances of financing options is crucial for turning creative concepts into tangible projects. In this guide, we’ll delve into the intricacies of film finance in India, exploring eligibility criteria, funding sources, application processes, interest rates, terms, and crucial considerations. Whether you’re a budding filmmaker seeking funding for your debut project or an experienced producer looking to navigate the complexities of financing, this guide aims to provide valuable insights to help you navigate the world of film financing in India effectively.

Eligibility Criteria

  • Project viability
  • Filmmaker track record
  • Budget alignment with industry standards
  • High-quality script
  • Compliance with legal requirements
  • Detailed production plan
  • Market analysis
  • Comprehensive financial plan

Types of Film Financing in India

  • Traditional financing options: bank loans, private equity investment.
  • Alternative funding sources: crowdfunding, angel investors, venture capitalists.
  • Government incentives and subsidies for film production.
  • Co-production agreements and international financing options.

Application Process

  • Submitting a project proposal with a synopsis and budget.
  • Providing required documentation.
  • Completing application forms.
  • Following specified timelines.
  • Communicating effectively.
  • Being prepared for negotiations.

Interest Rates and Terms

  • Understanding interest rates: fixed vs. variable, compound vs. simple interest.
  • Repayment terms: duration, grace periods, amortization schedules.
  • Collateral requirements and loan-to-value ratios.
  • Negotiating favorable terms with lenders and investors.

Risks and Considerations

  • Market risks: fluctuating audience preferences, competition from other films.
  • Production risks: delays, cost overruns, creative differences.
  • Distribution risks: securing distribution deals, marketing challenges.
  • Legal and regulatory risks: censorship issues, copyright disputes, tax implications.

Conclusion

Finance for film in India is dynamic and essential for the industry’s growth. Despite challenges, innovative approaches and collaborations drive success. By embracing technology and diversity, Indian cinema can continue to thrive globally.

Take the next step in your cinematic journey today. Contact us to discuss your film financing needs and unlock the potential of the Indian film industry.

Top 10 Finance Companies in India – 2024

When it comes to financial solutions in India, individuals often seek out the top 10 finance companies in India to fulfill their diverse needs. These companies, ranging from traditional banking giants to innovative non-banking financial corporations (NBFCs), play a crucial role in providing a wide array of financial products and services to cater to the Indian market.

Key Takeaways

Criteria for Selecting Top Finance Companies
Top 10 Finance Companies in India
Factors to Consider When Choosing the Best Loan Company
Best Loan Company in India at the Lowest Rate of Interest
Conclusion
FAQs:

Criteria for Selecting the Top 10 Finance Companies

Determining the top finance companies involves assessing various factors such as market reputation, customer satisfaction, financial performance, product offerings, and innovation.

Top 10 Finance Companies in India

Company NameInterest RateMinimum AgeMaximum AgeProcessing FeeLoan AmountLoan Tenure
HDFC BankStarting from 8.80%21 years60 yearsUp to 1.50% of the loan amount, Min. Rs. 2,999, Max. Rs. 25,000Up to Rs. 40 lakhsUp to 15 years
ICICI BankStarting from 8.35%23 years58 years (salaried), 60 years (self-employed)Up to 2.25% of the loan amount, Min. Rs. 2,000, Max. Rs. 25,000Up to Rs. 20 lakhsUp to 20 years
Axis BankStarting from 8.90%21 years60 yearsUp to 1.00% of the loan amount, Min. Rs. 10,000Up to Rs. 50 lakhsUp to 30 years
State Bank of India (SBI)Starting from 6.70%18 years70 years0.40% of the loan amount, Min. Rs. 10,000, Max. Rs. 30,000Up to Rs. 7.5 lakhsUp to 30 years
Bajaj FinservStarting from 8.30%23 years58 yearsUp to 4.13% of the loan amount, Min. Rs. 3,999, Max. Rs. 4,499Up to Rs. 25 lakhsUp to 25 years
Kotak Mahindra BankStarting from 10.25%21 years58 yearsUp to 2.50% of the loan amount, Min. Rs. 7,500Up to Rs. 20 lakhsUp to 20 years
IDFC First BankStarting from 10.49%23 years58 yearsUp to 2.00% of the loan amount, Min. Rs. 5,000Up to Rs. 40 lakhsUp to 15 years
Yes BankStarting from 10.25%21 years58 yearsUp to 2.50% of the loan amount, Min. Rs. 10,000Up to Rs. 50 lakhsUp to 25 years
Tata CapitalStarting from 10.99%23 years58 yearsUp to 2.50% of the loan amount, Min. Rs. 3,000Up to Rs. 25 lakhsUp to 6 years
Indiabulls Housing FinanceStarting from 8.50%21 years65 yearsUp to 2.00% of the loan amount, Min. Rs. 5,000, Max. Rs. 10,000Up to Rs. 50 lakhsUp to 30 years

Factors to Consider When Choosing the Finance Companies in India

When selecting a loan company, it’s essential to consider factors such as interest rates, loan terms, processing fees, customer service, and transparency.

Importance of Lowest Interest Rates

Lowest interest rates can significantly impact the overall cost of borrowing, making it crucial for borrowers to compare rates offered by different lenders to secure the most affordable option.

Best Loan Company in India at the Lowest Rate of Interest

The best loan company in India at the lowest rate of interest can vary depending on individual requirements and eligibility criteria. However, conducting thorough research, comparing offers, and reviewing customer feedback can help identify reputable lenders offering competitive rates.

Conclusion

In conclusion, the top finance companies in India play a crucial role in fueling economic growth and empowering individuals and businesses with access to financial resources. By evaluating key factors and understanding the importance of the lowest interest rates, borrowers can make informed decisions when choosing the top 10 finance companies in India to meet their needs.

FAQs

1. How do I determine the best finance company for my needs?

Ans: Consider your financial goals, and compare interest rates, fees, and customer reviews to find a company that aligns with your needs.

2. What factors influence the interest rates offered by finance companies?

Ans: Market conditions, company costs, borrower credit risk, loan terms, and regulatory requirements affect interest rates.

3. Are there any government regulations governing finance companies in India?

Ans: Yes, various government bodies regulate finance companies to ensure stability, integrity, and consumer protection.

4. How can I improve my chances of getting a loan with a lower interest rate?

Ans: Maintain a good credit score, stable income, and healthy financial profile. Compare loan offers and negotiate terms.

5. What role do credit scores play in loan approvals?

Ans: Credit scores reflect creditworthiness and help lenders assess risk. Higher scores lead to better loan terms and lower interest rates.

Top 10 Working Capital Loan in Kolkata

Introduction 

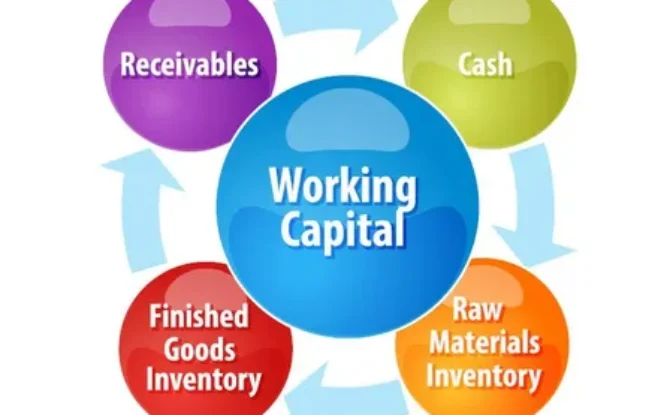
The Top 10 Working capital loan in Kolkata are specifically designed to meet the short-term financial needs of businesses, including managing inventory, paying salaries, and covering operational expenses. These loans play a vital role in ensuring the uninterrupted flow of operations and sustaining business growth. Working capital is the backbone of any business, ensuring smooth day-to-day operations and financial stability. In Kolkata, businesses often require working capital loans to bridge the gap between their short-term financial needs and available resources. However, finding the right loan provider offering the lowest interest rates can be challenging.

Importance of Working Capital 

Sufficient working capital is essential for businesses to maintain liquidity, seize growth opportunities, and withstand unexpected financial emergencies. It allows businesses to cover their day-to-day expenses and invest in expansion initiatives without compromising their operations.

Understanding Working Capital 

Kolkata, as a thriving commercial hub, offers a wide range of options for businesses seeking working capital loans. However, it is crucial for businesses to assess various factors before choosing a loan provider, including interest rates, loan terms, eligibility criteria, and additional benefits.

Factors to Consider When Choosing the Top 10 Working Capital Loan in Kolkata

  • Interest Rates: Option for lenders offering competitive interest rates to minimize borrowing costs and maximize profitability.
  • Loan Amount and Tenure: Evaluate your business needs and choose a loan provider offering flexible loan amounts and repayment tenures tailored to your requirements.
  • Eligibility Criteria: Ensure that your business meets the eligibility criteria set by the lenders to increase the chances of loan approval.
  • Additional Benefits: Look for loan providers offering additional benefits such as quick approval processes, online application facilities, and personalized customer service.

Top 10 Working Capital Loan in Kolkata

5 Providers Offering Lowest Interest Rates

ProviderInterest Rate
1Quick Loan8.0%
2PNB Housing Finance8.50% - 14.50%
3Loanz3608.90%
4Axis Bank11.40%
5Aditya Birla Finance11.25%

5 Providers Offering Additional Benefits

ProviderAdditional Benefits
1Tata CapitalOffers personal loans, home loans, business loans, and other loans
2Capital First Home Finance LtdOffers home loans
3All Capital FinanceOffers various types of loans
4Capital FloatOffers flexible loans
5Piramal Capital Housing FinanceOffers housing finance

Conclusion

Choosing the right working capital loan provider in Kolkata is crucial for the financial health and growth of your business. By considering factors such as interest rates, loan terms, eligibility criteria, and additional benefits, businesses can make informed decisions and secure the necessary funds to support their operations.

Top 10 Lease Rental Discounting Loan in Kolkata

Introduction

Lease Rental Discounting (LRD) loans are a popular financing option for property owners in Kolkata seeking to leverage their rental income. This article explores the top 10 Lease Rental Discounting loan in Kolkata and provides insights into securing the lowest rate of interest.

Factors Affecting Interest Rates for the Top 10 Lease Rental Discounting Loan in Kolkata

  • Credit Score:

Borrowers’ credit scores significantly influence the interest rates offered. A higher credit score often leads to lower interest rates

  • Loan Tenure:

The duration of the loan can impact the interest rates. LRD loan tenure typically ranges from 1 to 15 years, and longer tenures may affect the interest rates
  • Property Type and Location:

The type and location of the commercial property can affect the interest rates. Properties in prime locations may attract lower interest rates

  • Lender’s Policies:

Different lenders may have varying interest rate structures based on their internal policies and risk assessments
  • Borrower’s Financial Profile:

The financial stability and profile of the borrower, including income, existing liabilities, and business stability, can influence the interest rates offered

  • Rental Income Stability:

The stability and quality of the rental income stream from the property can impact the interest rates

Top 10 Lease Rental Discounting Loan in Kolkata

ProviderRating
Fair Finance4.7249
The Corporate Financial Services5.07
Indexia FinanceNot specified
PNB Housing FinanceNot specified
J D SalesNot specified
M K Ventures4.9
My Loan Buddy1.7
Mahalaxmi Consultancy-Loan Facilitator4.9
Credit Cares4.9
KreditDeals4.9

Eligibility Criteria for Availing Top LRD in Kolkata

  • Age Criteria:

The applicant must be 21 years or above but not more than 60 years in the case of a salaried person and 65 years in the case of self-employed individuals.

  • Property Ownership:

The borrower must possess a property leased to a known brand, corporate, public sector undertaking, government, semi-government, or multinational company
  • Lease Agreement Period:

The lease period is a critical factor, with banks typically providing loans for properties with lease periods of 5 to 10 years.
  • CIBIL Score:

A good credit score, usually a CIBIL score of 700 or above, is preferred for loan approval
  • Income Source:

The loan is available for salaried individuals, self-employed professionals, and various types of companies and firms
  • Documentation:

The applicant needs to provide necessary documents such as lease agreements, income tax returns, balance sheets, and bank statements.

Conclusion

Lease Rental Discounting (LRD) is a financial instrument that provides significant benefits for lessors. Understanding its concept, benefits, and process is crucial for maximizing its potential. By leveraging LRD, lessors can secure a steady income stream, enhance liquidity, and mitigate risks effectively.